
By CleanTechnica Staff
Despite a volatile regulatory environment, the sudden termination of federal consumer incentives, and unprecedented geopolitical instability affecting global energy markets, the transition to electric vehicles (EVs) in the United States is proving remarkably resilient. Legacy automakers—including industry heavyweights like Toyota, Ford, and Subaru—are continuing to double down on electrification.
A landmark study released by Harvard University economists underscores this dynamic. Originally predicting that EVs would claim 32% of new vehicle sales in the US by the end of the decade, researchers have since revised that forecast upward to an impressive 38%. This projection represents a dramatic acceleration from the 8% market share recorded in 2025.
While policy shifts under the Trump administration have introduced friction into the American automotive market, converging factors—ranging from sustained high fossil fuel prices to rapidly maturing battery technology and expanding public charging infrastructure—suggest that vehicle electrification has crossed a threshold of unstoppable momentum.
Main Facts: The 2030 Outlook and Market Realities
The modern American EV landscape exists in a state of stark contrasts. On one hand, the domestic market experienced a severe contraction following the legislative elimination of the all-important $7,500 federal EV tax credit. On the other hand, long-term economic models suggest that market fundamentals have permanently shifted away from internal combustion engines (ICE).
Key takeaways from the current market and recent economic modeling include:
- The Harvard Revision: Published by the Salata Institute for Climate and Sustainability, a July study titled Simulating Impacts of Trump Policy Changes on Electric Vehicle (EV) Adoption initially estimated a 32% EV market share by 2030. In September, the Harvard Gazette updated that figure to 38%, driven by stronger-than-expected organic market growth.
- The Impact of the OBBA: The elimination of the $7,500 tax credit—enacted via the administration’s "One Big Beautiful Bill" (OBBA) tax legislation—was found to be the single most damaging policy change, accounting for a projected 6.2 percentage point drop in 2030 adoption rates.
- The New Baseline: Even with the loss of federal consumer incentives and various regulatory rollbacks, a 38% adoption rate represents nearly a fivefold increase over 2025 levels (8%).
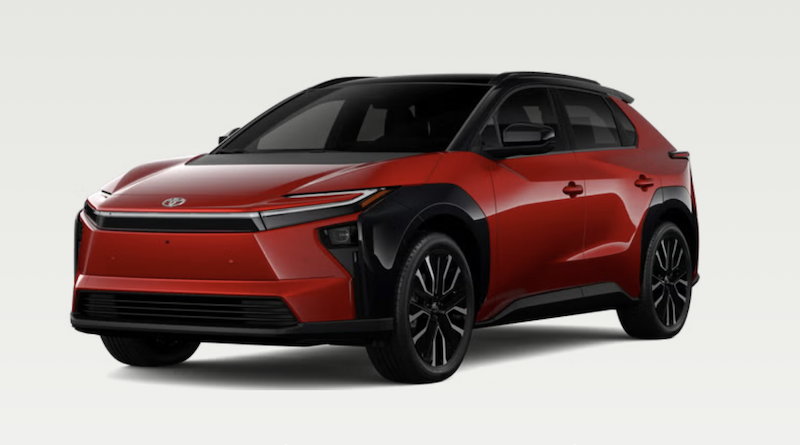
- Legacy Automaker Pivot: Far from abandoning the segment, traditional manufacturers are aggressively filling out their portfolios. Toyota has expanded its bZ lineup, Subaru has introduced new offerings like the Solterra Trailseeker, and Ford is preparing volume production for affordable models such as the upcoming sub-$30,000 Fathom electric pickup truck.
Chronology: A Timeline of Policy Shifts and Market Shocks
To understand how the US EV market arrived at its current trajectory, it is necessary to examine the sequence of legislative, geopolitical, and economic milestones that have shaped the sector from 2024 through late 2026.
December 2024: The Baseline Policy Era
Prior to the inauguration of the current administration, the baseline for American transportation policy relied heavily on the Biden-era incentives established by the Inflation Reduction Act (IRA). Under these rules, economists projected a robust 48% EV adoption rate by 2030, supported by consumer tax credits, manufacturing subsidies, and stringent fleet emissions standards.
Early 2025: Executive Actions and Legislative Overhauls
Upon taking office, the Trump administration moved swiftly to dismantle climate-related regulations and executive orders.
- The NEVI Freeze: In early 2025, the administration ordered a sudden halt to the $5 billion National Electric Vehicle Infrastructure (NEVI) program, a bipartisan initiative designed to build out fast-charging corridors across interstate highways.
- The "One Big Beautiful Bill" (OBBA): Congress passed the sweeping tax and budget reconciliation package dubbed the OBBA. Among its primary provisions was the immediate termination of the $7,500 federal consumer tax credit for new, used, and commercial EV purchases, as well as retail leases.
February 28, 2026: Global Energy Markets Fractur
A major geopolitical turning point occurred when the administration launched a military conflict in Iran. The resultant closure of the Strait of Hormuz—a vital maritime chokepoint for global oil shipments—triggered widespread disruption across Middle Eastern energy infrastructure.
Simultaneously, the administration’s hesitant diplomatic approach toward Russia enabled Vladimir Putin’s ongoing war in Ukraine to continue taking a heavy toll on international energy supplies. Global fuel prices skyrocketed, dragging American gas prices upward and creating sustained economic pressure at the pump.
Mid-2026: Judicial Interventions and Institutional Studies
- May–June 2026: Federal courts intervened in the administration’s infrastructure rollbacks, overturning the executive freeze on the NEVI program and allowing state-level collaborative fast-charging construction to resume. Meanwhile, legacy automakers accelerated product rollouts, with Subaru and Toyota debuting new EV variants designed to appeal to mainstream buyers without relying on federal subsidies.
- July 6, 2026: The Salata Institute at Harvard University published its initial simulation of Trump-era policy impacts on EV adoption, forecasting a resilient 32% market share by 2030 despite the loss of the tax credits.
- September 17, 2026: The Harvard Gazette issued a formal revision to the study, upgrading the 2030 forecast to 38% based on updated data reflecting rapid improvements in battery economics and charging network density.
Supporting Data: Harvard’s Economic Simulations
The Harvard Salata Institute study provides granular insight into which specific policy changes hurt the market and which had minimal impact.
Using sophisticated economic modeling, the researchers isolated the effects of various components within the OBBA and executive branch directives:
| Policy Factor | Impact on 2030 EV Market Share (Percentage Points) |
|---|---|
| Baseline (December 2024 Policies) | 48.0% |
| Elimination of Purchase/Lease Tax Credits (OBBA) | -6.2 pts |
| Other OBBA Regulatory & Tax Adjustments | -2.4 pts |
| Adjusted Total under Current Policy Framework | ~38.0% |
The data reveals a critical narrative: while the loss of the $7,500 credit is undeniably a headwind—eradicating roughly 6.2 percentage points of potential market share—the remaining 38% adoption rate demonstrates that market forces have evolved beyond absolute dependence on government subsidies.
Technology and Cost Reductions
The Harvard findings emphasize that the EV landscape of 2026 bears little resemblance to the nascent market of the early pandemic era. During COVID-19, temporary spikes in fuel prices failed to permanently alter consumer habits because EV technology was still maturing, upfront purchase prices were prohibitive, and charging infrastructure was sparse.
By contrast, the mid-2026 market benefits from:
- Declining Battery Costs: Next-generation chemistry has significantly lowered the manufacturing cost of battery packs, allowing automakers to achieve price parity with internal combustion vehicles sooner than previously anticipated.
- Extended Driving Ranges: Modern packs provide greater energy density, reducing range anxiety and making EVs practical primary vehicles for long-distance drivers.
- Pervasive Charging Infrastructure: Despite federal policy shifts, private capital has flooded the charging sector. Quick-serve restaurants, retail centers, and highway corridors have rapidly deployed fast-charging stations, complemented by an emerging network of urban curbside chargers.
Official Responses and Industry Reactions
Automotive executives and market analysts have offered mixed reactions to the shifting regulatory landscape, though the overarching sentiment remains cautiously optimistic.
Legacy Automakers Press Forward
Rather than retreating from electrification, legacy brands are recalibrating their manufacturing strategies to appeal directly to cost-conscious consumers.
- Toyota: Long a proponent of a diversified powertrain strategy—balancing hybrids, plug-in hybrids, and battery EVs—Toyota continues to roll out its bZ series. Company leadership has noted that consumer demand for efficient vehicles remains high, driven primarily by unpredictable fuel costs rather than government mandates.
- Ford: Positioning itself for high-volume, low-cost EV production, Ford has continued pre-gaming for its upcoming Fathom electric pickup truck. With a targeted retail price under $30,000, the vehicle aims to capture the working-class and commercial fleet markets that historically relied exclusively on gasoline-powered trucks.
- Subaru: By introducing adventurous, all-wheel-drive entries like the Solterra Trailseeker, Subaru is successfully translating its brand loyalty into electric conversions, proving that regional niche buyers are ready to make the switch.
Policy Analysts and Economists
The authors of the Harvard study maintain that while legislative rollbacks have slowed the pace of adoption—trimming the 2030 ceiling from 48% to 38%—they have fundamentally failed to derail the energy transition.
"The elimination of the EV-related tax credits is a significant fiscal hurdle," the study’s authors noted in their summary. However, they emphasize that once an industry reaches a certain threshold of technological maturity and cost reduction, consumer behavior is increasingly dictated by operational savings, vehicle performance, and the sheer inconvenience of fossil fuel infrastructure.
Implications: The "New Normal" for American Transportation
The convergence of geopolitical conflict, legislative policy, and technological progress holds profound implications for the future of American mobility.
1. The End of the "Gas Desert" Era
Retail gasoline infrastructure is undergoing a quiet contraction. As the retail gas industry consolidates, many urban and rural areas face the "gas desert" phenomenon, where traditional fueling stations are closing faster than they open. Conversely, the proliferation of destination charging, workplace chargers, and fast-charging retail hubs means that refueling—or rather, recharging—is becoming integrated into daily routines. For many drivers, plugging in at home or while running errands is rapidly proving far more convenient than visiting a dedicated gas station.
2. Geopolitical Vulnerability as a Catalyst for Electrification
The ongoing instability in the Middle East and Eastern Europe has demonstrated that reliance on fossil fuels exposes national economies to perpetual price shocks. While geopolitical conflicts carry severe human and economic costs, they also serve as a harsh macroeconomic reminder that domestic electricity—generated via a diverse mix of solar, wind, nuclear, and domestic grid resources—offers long-term price stability that oil markets can never match.
3. Subsidies as Training Wheels, Not Permanent Fixtures
The Harvard findings suggest that government incentives served their primary purpose: they successfully jump-started the domestic EV market through its most vulnerable infancy. Now that supply chains are established, manufacturing scale is increasing, and battery prices are falling, the market is demonstrating the capacity to stand on its own feet.
Even under adverse policy conditions marked by the loss of tax credits and regulatory friction, a projected 38% market share by 2030 indicates that the electric vehicle movement in the United States is no longer a fragile experiment. It has become the definitive future of the automotive industry.
